Home loan for self-employed business owners and professionals in Thane and Mumbai: Your family's bigger home, made possible.
- A lender who reads your business
- Without extra effort from you
- Even if your ITR is tax-efficient
What clients say
5.0 ★ on Google, 27 reviewsNew home loan for self-employed business owners · Thane & Mumbai
The home your business has earned, planned the right way.
The home your business has earned, without extra effort on your side, even if your income comes from more than one source.
Lenders read business income in different ways. Some count only profit; others also read your banking and GST.
How we helpWe read your ITR, banking and GST the way a credit officer does, then go to the lenders that read your business best.
Tell us four things and we'll send your exact list on WhatsApp.
Home loan balance transfer for self-employed business owners · Thane & Mumbai
Keep your home. Own it years sooner.
More of your income for your family and business every month, without redoing your paperwork, even if your income changes year to year.
Your business is stronger than when you first borrowed. Your rate can reflect that.
How we helpWe work out your real saving after all costs first, and move your loan only when it clearly pays. Need extra funds too? We can add a top-up in the same transfer.
Tell us four things and we'll send your exact list on WhatsApp.
Home loan top-up for self-employed business owners · Thane & Mumbai
Your next big plan, funded by the home you own.
Funds for your business or family, without an expensive unsecured loan, even if your home loan is with another bank.
A top-up on your home loan usually costs far less than an unsecured business loan.
How we helpWe check what your property and repayment record can raise, and find the lender that gives it at the lowest full cost. If your rate is high, we can move your loan with a top-up.
Tell us four things and we'll send your exact list on WhatsApp.
From first call to funds in your account
The home your family wants, backed by the business you built, without visiting bank after bank, even if your income changes year to year.
Review
Your ITR, banking and GST read the way a bank reads them, before you apply.
Match
Only lenders whose policy suits a business owner like you.
Compare
Rate, fees and terms of every offer, side by side.
Disburse
With you until the money reaches your account.
Our commitment: we work to get you the full amount your plan needs, so every part of it is covered.
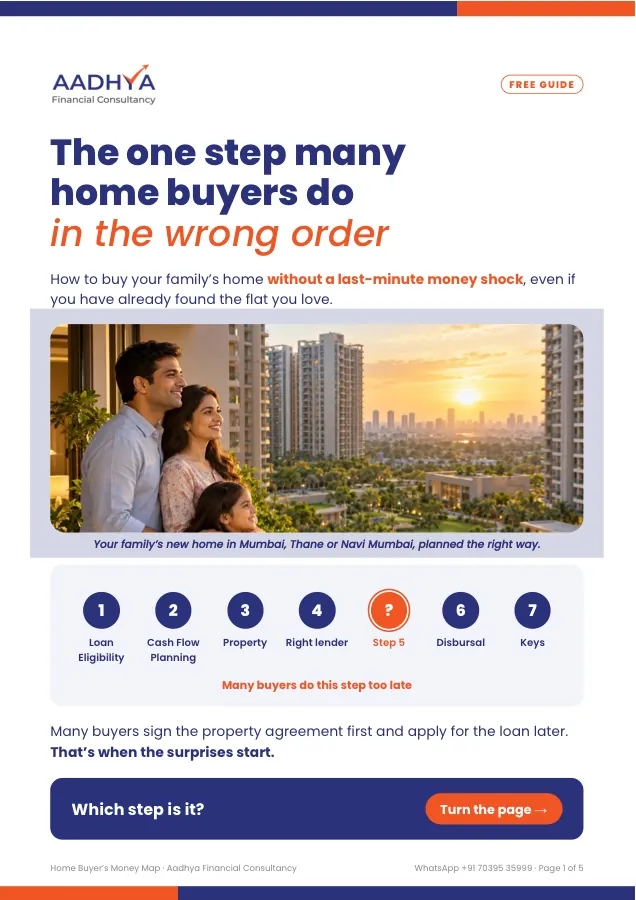
Home Buyer's Money Map
One step, done at the right time, keeps your whole home budget on track. This short guide shows you which step it is, and the 7 steps from "Can I afford it?" to the keys in your hand.
- The step to do before you sign
- The full cash plan, beyond the loan
- A worksheet for your own numbers
Home loan questions, answered
How much home loan can a self-employed person get?
It depends on your income as per ITR (with depreciation and some items added back), your existing EMIs, the tenure and the lender's method. Some lenders also read banking or GST turnover. A 20-minute call gives a realistic figure for you.
How much of the property value will the bank fund?
Under RBI limits, lenders can fund up to 90% of the property value for loans up to Rs 30 lakh, up to 80% for loans of Rs 30 lakh to Rs 75 lakh, and up to 75% for loans above Rs 75 lakh. The rest is your own contribution, and each lender decides within these limits.
My CA keeps my profit low to save tax. Will that reduce my loan?
It can, because most lenders start from declared profit. Planning tax and your loan together before the year closes helps, and some lenders have programmes that read business income more fully. We'll show you which route suits you.
When does a home loan balance transfer make sense?
When the new rate is meaningfully lower and a good part of the tenure is still ahead, so the saving is more than the processing and legal costs. We work this out with you before you move.
Can my spouse or business partner be a co-applicant?
An earning spouse can usually be a co-applicant and add to your eligibility. A business partner can join only if they are also a co-owner of the property, depending on the lender.
What documents do I need?
Typically your last 2 to 3 years' ITR with computation, 12 months' main bank account statement, GST return summary, details of existing loans and the property papers. We give you a checklist for your case.
Your next step: a 20-minute discovery call
In 20 minutes you'll know:
- Roughly how much your business income supports
- Which lenders suit your profile
- What to set right before you apply
There's no pressure. We'll just see if we can help.