Home loan for salaried professionals in Thane and Mumbai: Your family's dream home, made possible.
- The right lender for you
- Without extra effort from you
- Even if it's your first home
What clients say
5.0 ★ on Google, 27 reviewsNew home loan for salaried professionals · Thane & Mumbai
Your family's home, planned the right way.
The right home loan for your new home, without visiting bank after bank, even if part of your salary is variable pay.
The same salary can get a very different loan amount at different lenders. It all depends on how your income is read.
How we helpWe read your salary the way a credit officer does, then take your file only to the lenders that count all of it.
Tell us three things and we'll send your exact list on WhatsApp.
Balance transfer for salaried professionals · Thane & Mumbai
Keep your home. Own it years sooner.
More of your salary for your family every month, without redoing your paperwork, even if you've been paying your loan for years.
Your rate may have been right when you borrowed. Today's lenders may offer you better, and over the remaining years the saving adds up.
How we helpWe work out your real saving after all costs first, and move your loan only when it clearly pays. Need extra funds too? We can add a top-up in the same transfer.
Tell us three things and we'll send your exact list on WhatsApp.
Home loan top-up for salaried professionals · Thane & Mumbai
Your family's next big plan, funded by the home you own.
Funds for renovation, education or a wedding, without a costly personal loan, even if your home loan is with another bank.
A top-up on your home loan usually costs far less than a personal loan, and can run for many more years.
How we helpWe check what your property and repayment record can raise, and find the lender that gives it at the lowest full cost. If your rate is high, we can move your loan with a top-up.
Tell us three things and we'll send your exact list on WhatsApp.
From first call to funds in your account
The home your family wants, with the right lender behind you, without extra effort on your side, even if part of your salary is variable pay.
Review
Your papers read the way a bank reads them, before you apply.
Match
Only lenders whose policy suits your profile.
Compare
Rate, fees and terms of every offer, side by side.
Disburse
With you until the money reaches your account.
Our commitment: we work to get you the full amount your plan needs, so every part of it is covered.
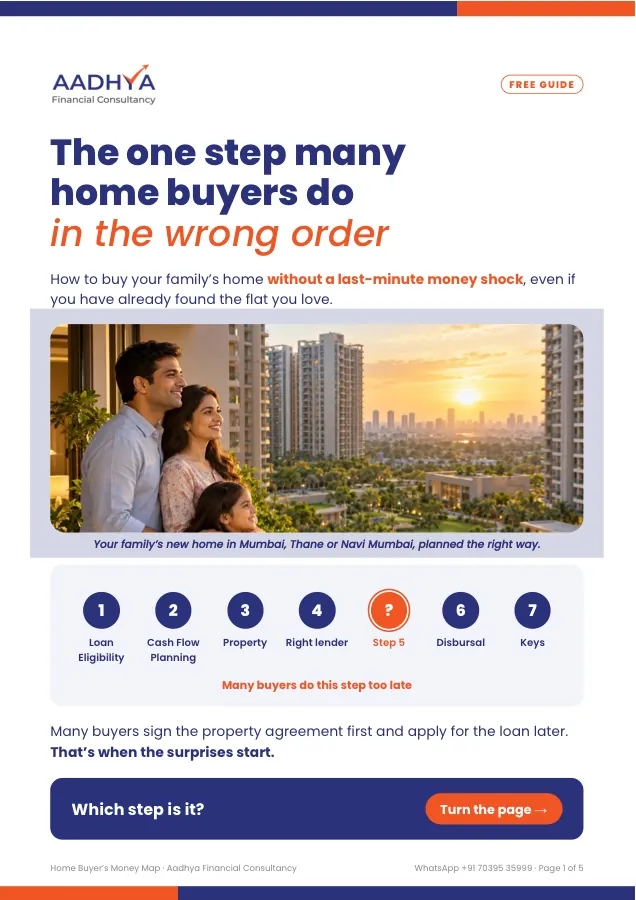
Home Buyer's Money Map
One step, done at the right time, keeps your whole home budget on track. This short guide shows you which step it is, and the 7 steps from "Can I afford it?" to the keys in your hand.
- The step to do before you sign
- The full cash plan, beyond the loan
- A worksheet for your own numbers
Guides for salaried home buyers
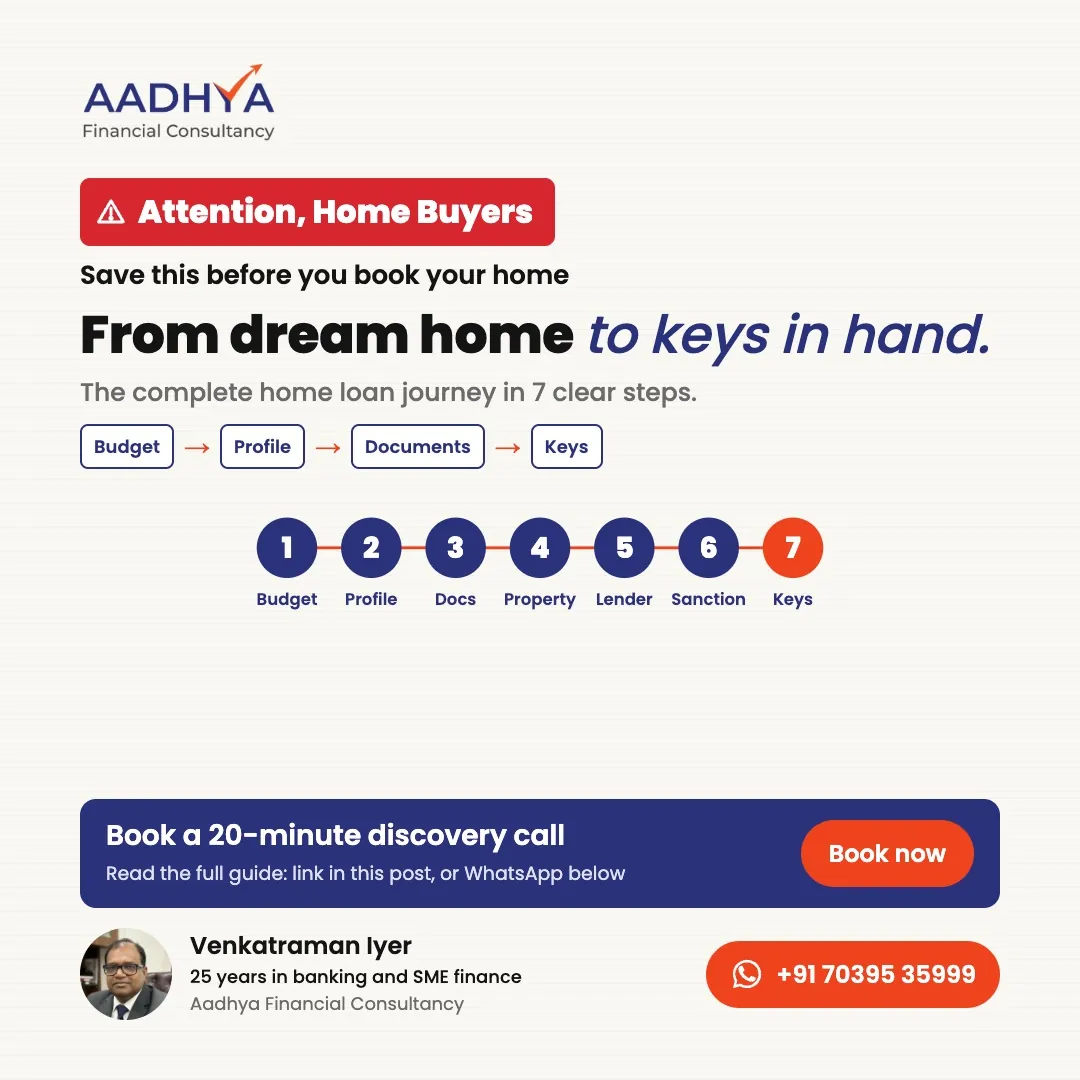
The Home Loan Checklist: From Dream Home to Keys in Hand
The complete home loan journey in 7 clear steps, with every document in place, even on your first home.
Read the article →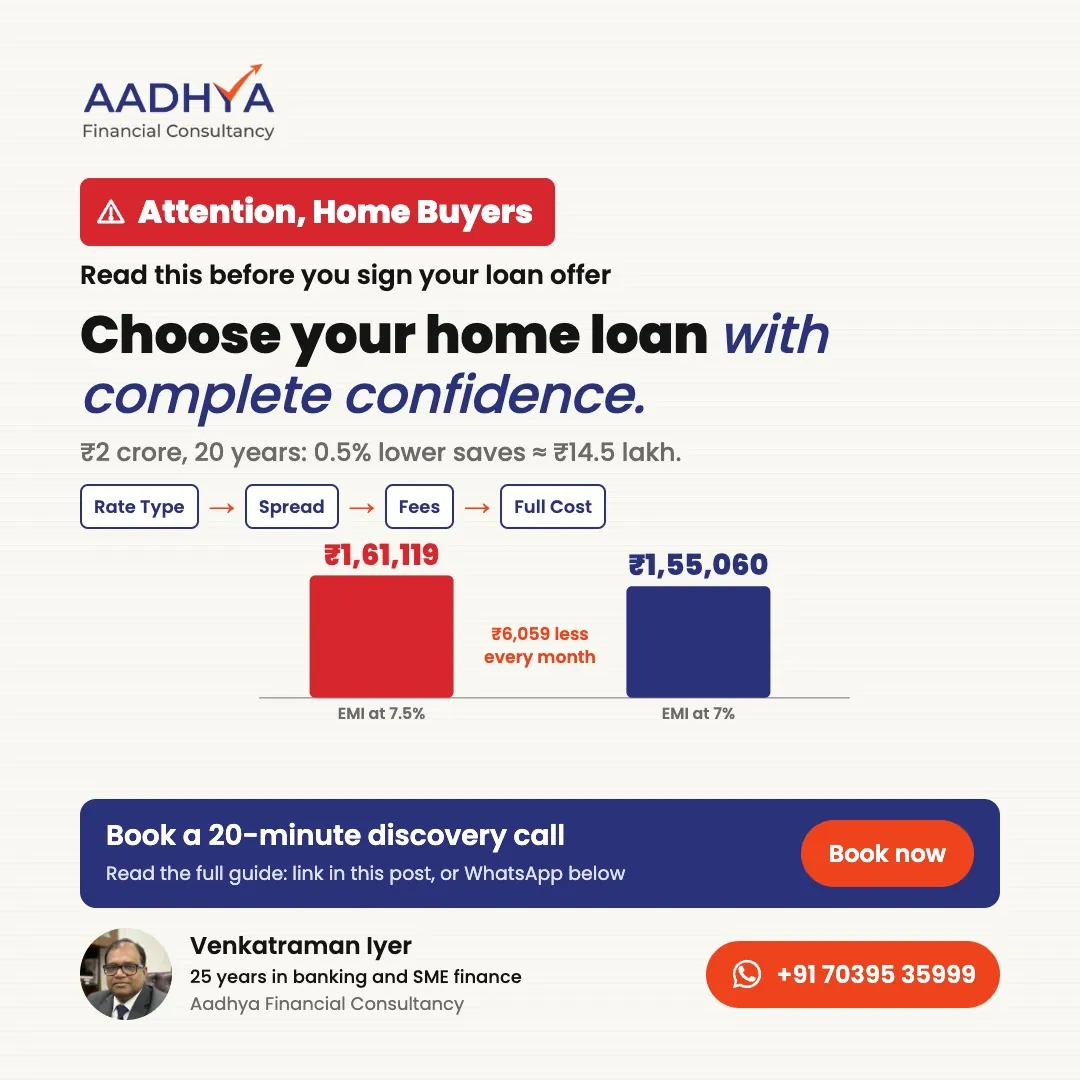
Six Things Smart Buyers Understand Before Taking a Home Loan
Floating or fixed, the bank's margin, fees, insurance, prepayment and tenure: the six things that decide what your home loan really costs.
Read the article →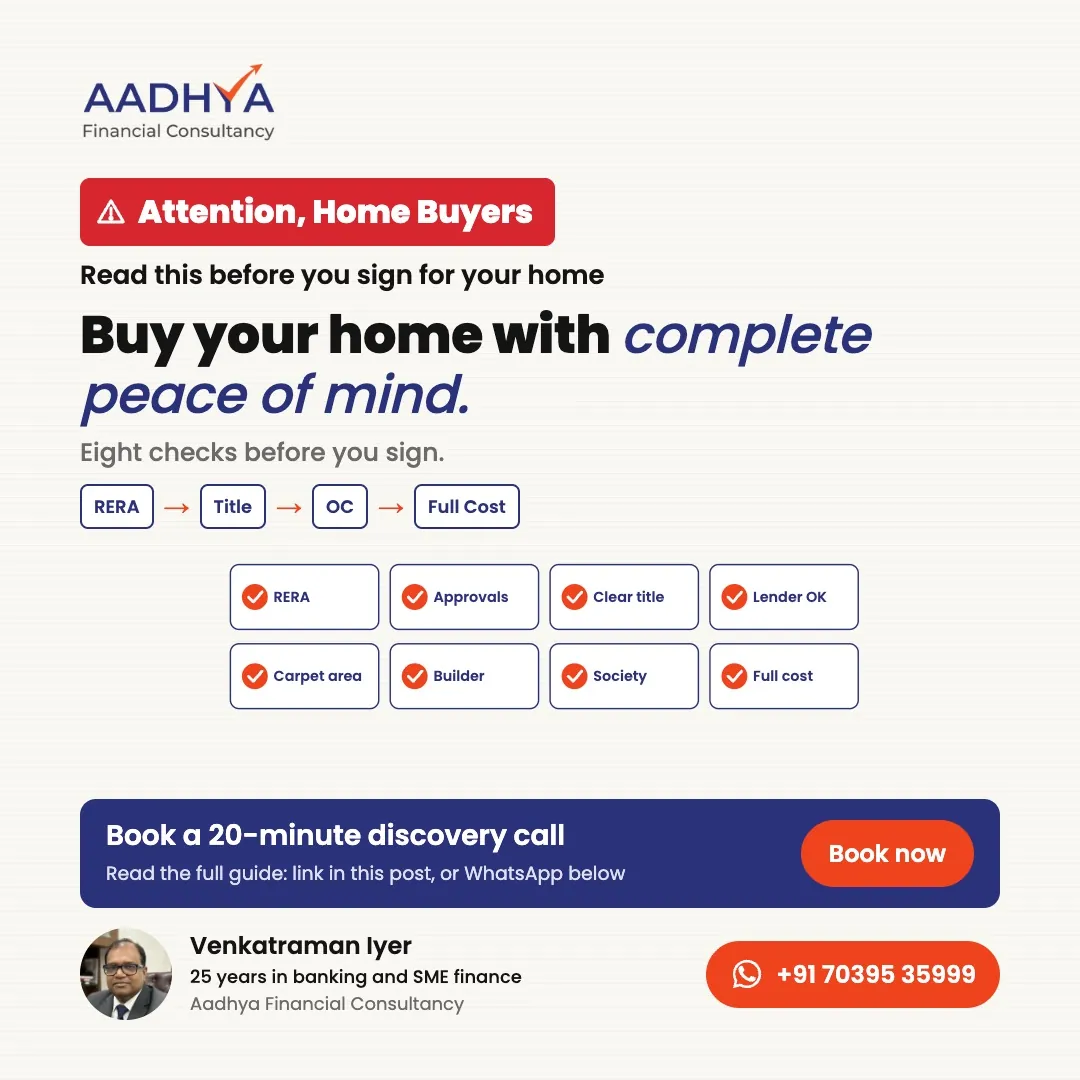
Eight Things to Check Before Buying a Home
RERA, approvals, clear title, lender approval, carpet area, builder record, society papers and the full cost: eight checks before you sign.
Read the article →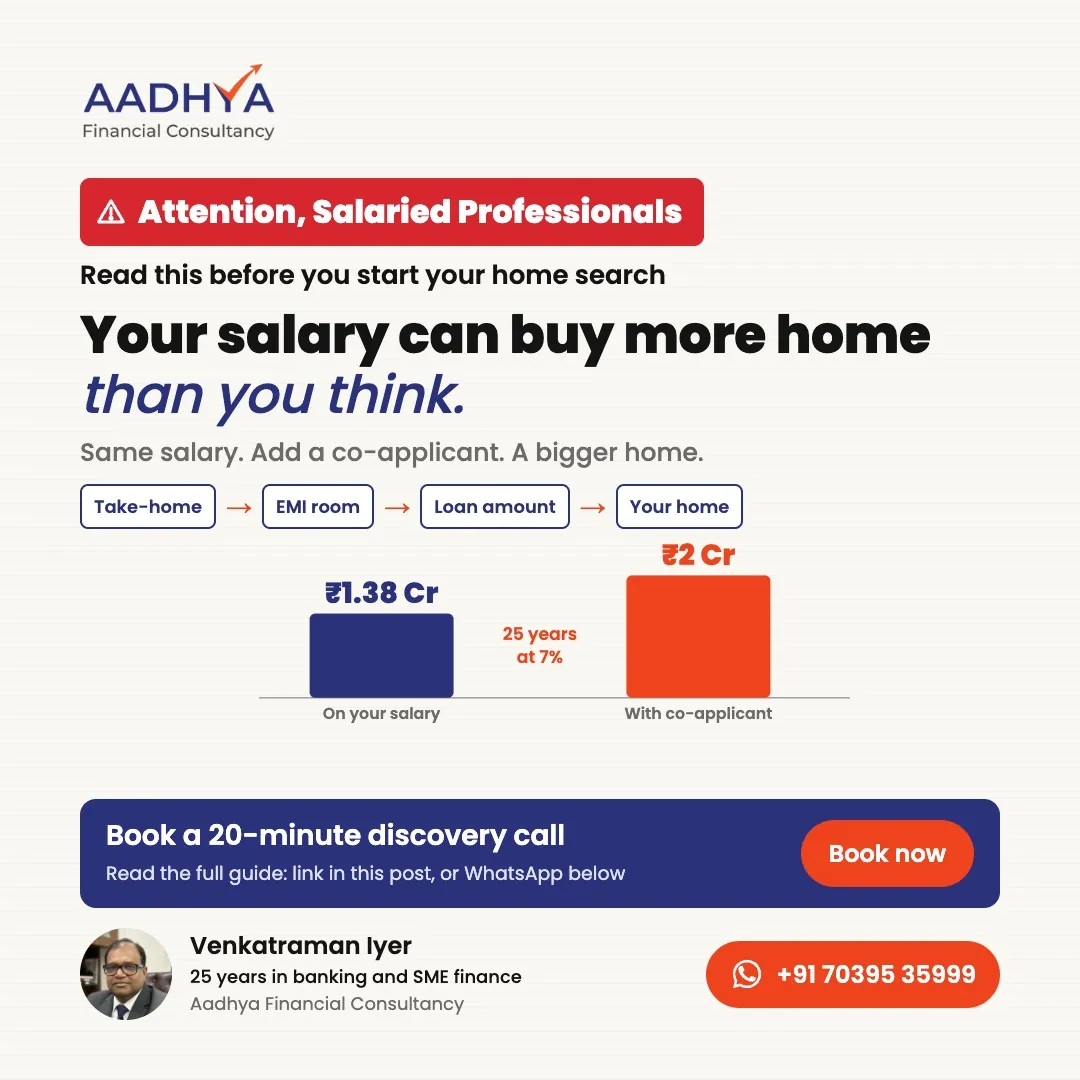
How Much Home Loan Can I Get on My Salary?
A 10-minute method to work out your home loan eligibility from your take-home salary, with a worked example and four ways to grow it.
Read the article →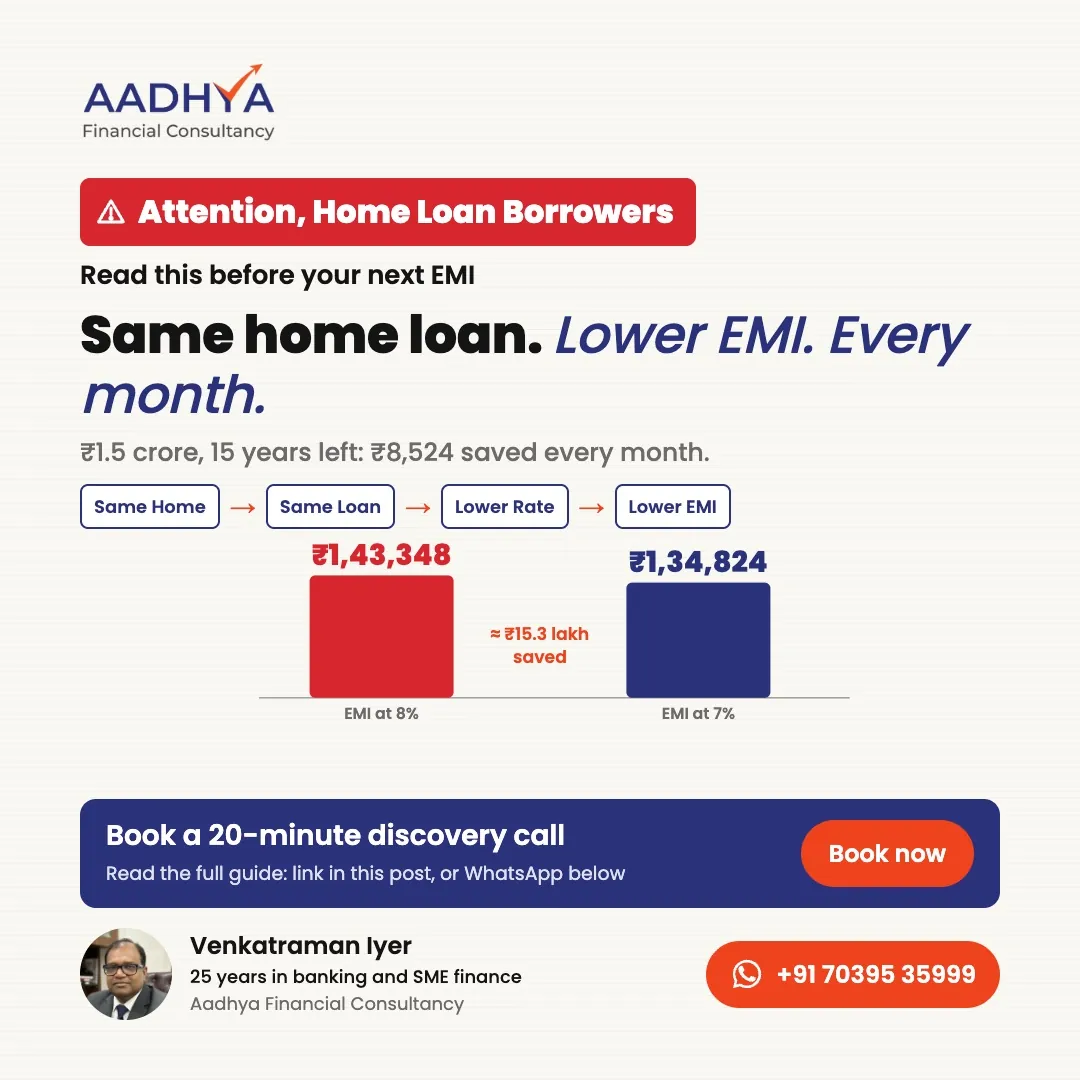
Home Loan Balance Transfer: How to Work Out Your Saving
When moving your home loan to a lower rate makes sense, a 3-step way to calculate your saving, and a worked example in rupees.
Read the article →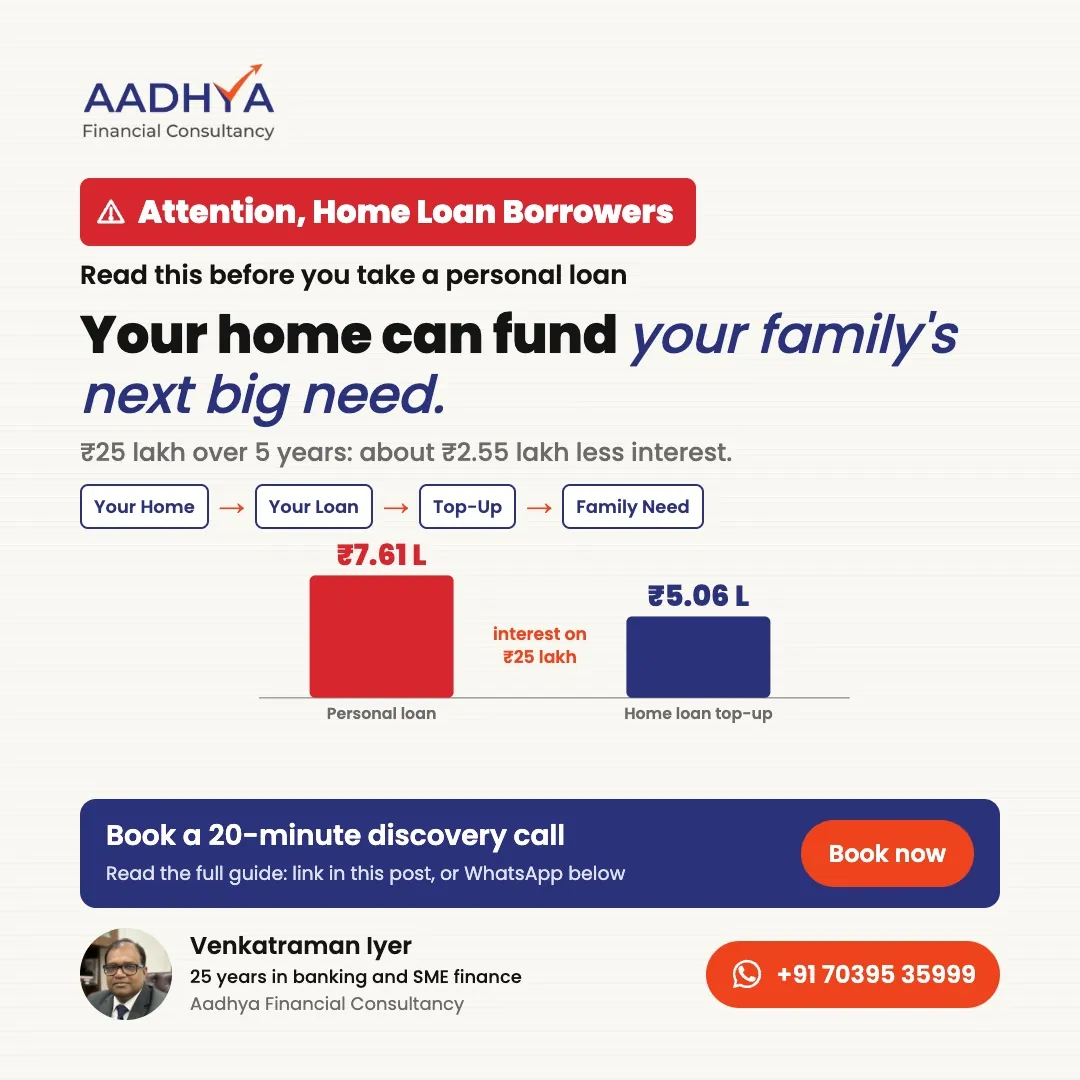
Home Loan Top-Up: The Smart Way to Fund Your Family's Big Needs
Fund renovation, education or a wedding at home-loan cost. Top-up and personal loan compared side by side in rupees.
Read the article →Home loan questions, answered
How much home loan can I get on my salary?
It depends on your take-home salary, your existing EMIs, the tenure and the lender's policy. As an illustration, Rs 1 lakh take-home with no other EMIs can support about Rs 1.03 crore over 25 years at a typical current rate. A co-applicant can increase it, and a 20-minute call gives a realistic figure for you.
How much of the property value will the bank fund?
Under RBI limits, lenders can fund up to 90% of the property value for loans up to Rs 30 lakh, up to 80% for loans of Rs 30 lakh to Rs 75 lakh, and up to 75% for loans above Rs 75 lakh. The rest is your own contribution, and each lender decides within these limits.
When does a home loan balance transfer make sense?
When the new rate is meaningfully lower and a good part of the tenure is still ahead, so the saving is more than the processing and legal costs. We work this out with you before you move.
Can I take a top-up along with a balance transfer?
Yes. Many lenders offer a top-up with the transfer, based on your property's value and repayment record, in one process.
What documents do I need for a home loan?
Typically identity and address proof, recent salary slips, bank statements, Form 16 and the property papers. We give you a checklist for your case.
Can my spouse be a co-applicant?
Yes. Adding an earning spouse or parent as co-applicant can increase the amount you are eligible for.
Your next step: a 20-minute discovery call
In 20 minutes you'll know:
- Roughly how much you can borrow
- Which lenders suit your profile
- How to strengthen your application
There's no pressure. We'll just see if we can help.