How to move your home loan to a lower rate and keep the saving for your family, in one smooth switch, even midway through your loan.
When you took your home loan, you chose the best option available at that time. Since then, your salary has grown, your repayment record has built up, and lenders' rates have moved. That makes your profile stronger today than on the day you signed, and a stronger profile can earn a better rate.
The new way to look at your home loan
Your home loan is not a lifelong commitment to one lender. It is a contract you can re-price. A balance transfer moves your outstanding loan to a lender that offers you a lower rate. The home stays the same; only the cost changes.
Work out your saving in 3 steps
- Note your outstanding loan and remaining tenure. Your lender's latest statement shows both.
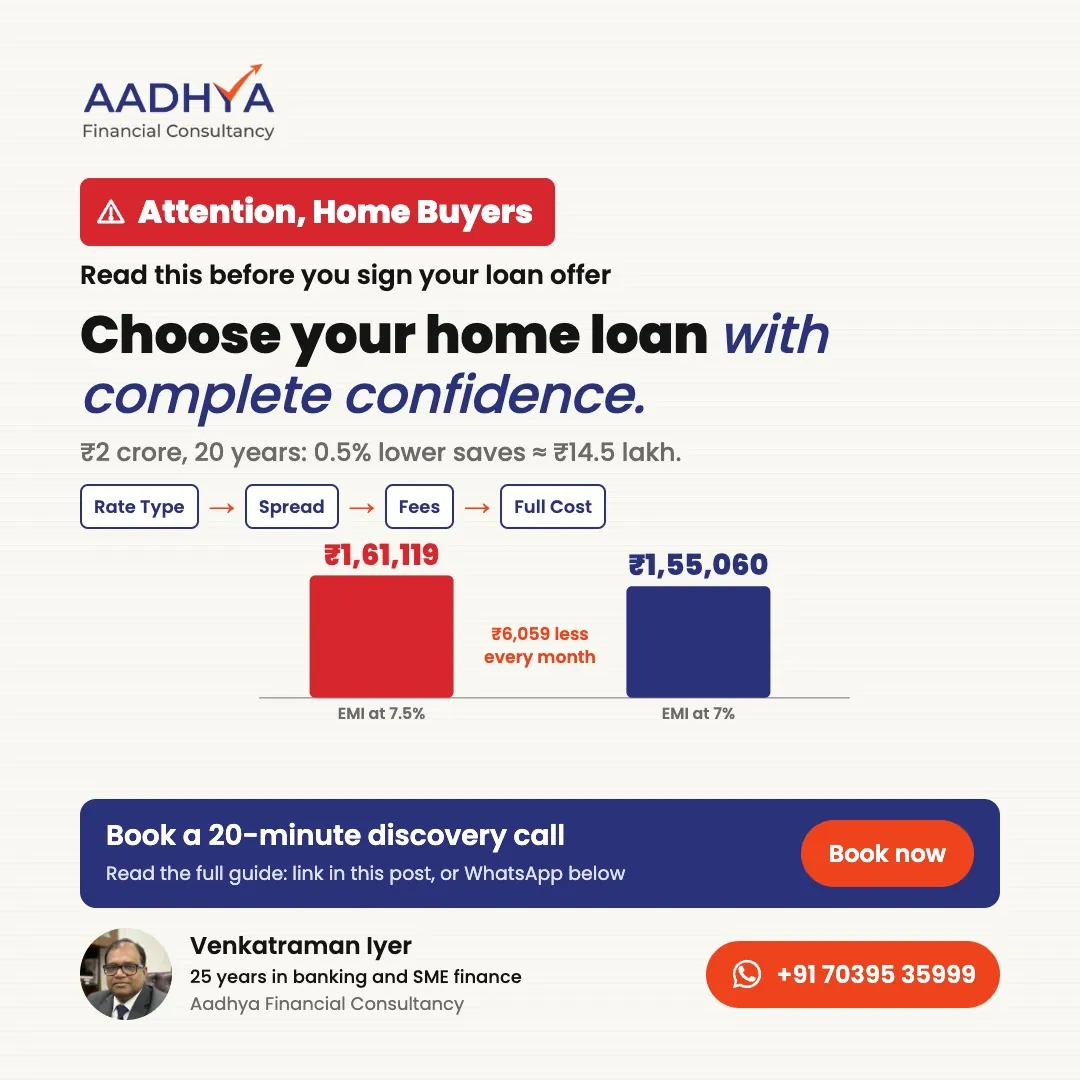
- Compare the EMI at the two rates. Use the EMI calculator for your current rate and the new rate, with the same remaining tenure.
- Weigh the saving against the switching costs. Processing and legal charges are a one-time cost; the EMI saving repeats every month.
A worked example
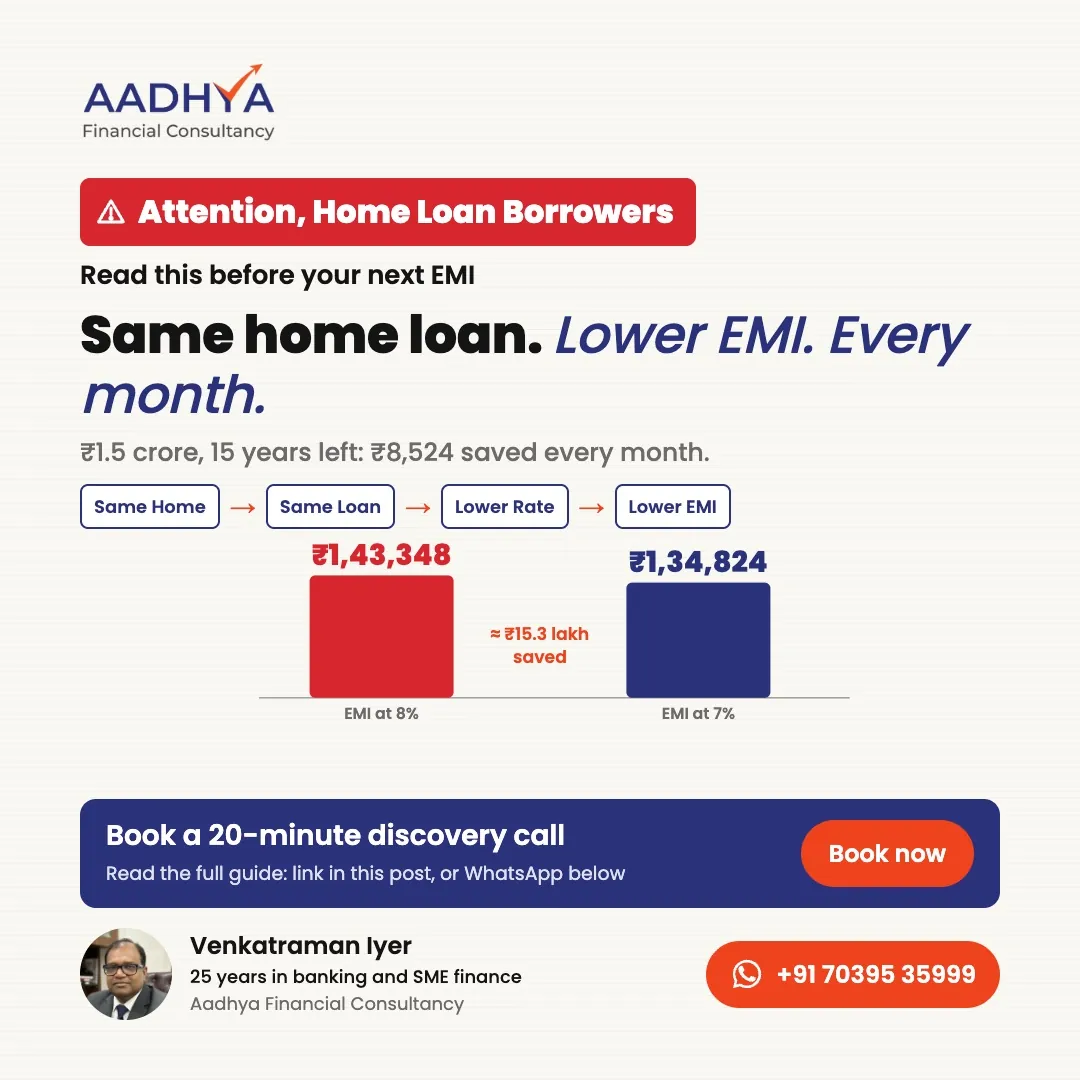
Rahul has Rs 1.5 crore outstanding with 15 years to go, at 8%.
- His current EMI: Rs 1,43,348
- At 7% with a new lender: Rs 1,34,824
- Saving: Rs 8,524 every month, or about Rs 15.3 lakh over the remaining 15 years
He then has a choice:
- Keep the lower EMI and enjoy Rs 8,524 more every month, or
- Keep paying Rs 1,43,348 and finish his loan about 18 months earlier.
Even after one-time switching costs of, say, Rs 1 lakh, the saving is many times larger.
Figures are illustrations to show the method, not an offer.
When a balance transfer works best
- A meaningful difference in rate. The bigger the gap, the faster the saving builds.
- A good part of the tenure still ahead. The longer the remaining term, the larger the total saving.
- A steady repayment record. On-time EMIs on your current loan are exactly what the new lender values.
- The option of a top-up. Many lenders let you add extra funds during the switch, in one process.
Do it yourself, or have me by your side
You can compare offers, apply to a new lender and manage the paperwork with both banks yourself.
Or I can do the numbers with you first, so you know your exact saving before you decide. I take your application to the lenders that offer the best terms for transfers, and handle the paperwork with both lenders alongside you, until your old loan is closed and the new one is running.
Frequently asked questions
Is a home loan balance transfer worth it?
It is worth it when the total saving is clearly more than the one-time switching costs. That usually means a meaningful rate difference and a good part of the tenure still to go.
Can I take a top-up with a balance transfer?
Yes. Many lenders offer a top-up along with the transfer, based on your property's value and repayment record.
Will my EMI go down or my tenure?
Your choice. You can lower the EMI, or keep the EMI and finish the loan sooner.
Your next step
In a 20-minute discovery call, we'll work out your saving and the lenders that suit your profile.
Book a 20-minute discovery call There's no pressure. We'll just see if we can help.
Read more: Home loan balance transfer for salaried professionals
Disclaimer: This article is for general information only and is not financial advice. Aadhya Financial Consultancy is a loan advisory firm working with banks and NBFCs; it does not lend. Rates and terms depend on each lender's assessment. Figures are illustrations.
I spent 15 years inside banks learning how a lender reads a loan. Since 2017, I've used it only on the borrower's side.
More about me →