How to choose a home loan with complete confidence, by understanding six things in the offer, even if finance isn't your field.
A home loan runs for 15, 20 or 25 years. The few minutes you spend understanding the offer pay back every month for that whole time. Here are the six things smart buyers look at.
The new way to look at a home loan offer
The best home loan is the one with the lowest full cost over its life, not the one with the lowest headline rate. Rate, fees, tenure and flexibility together decide what you really pay.
Six things to understand
1. Floating or fixed rate
Most home loans in India are floating: the rate moves with the lender's benchmark. Fixed rates stay the same for a set period, usually at a higher starting rate. Know which one you have and how it resets.
2. The benchmark and the spread
Floating rates are linked to a benchmark (such as the repo rate) plus a spread. The spread is set at the start and reflects your profile. A strong profile earns a lower spread, and that saving lasts for the whole loan.
3. Processing and other one-time fees
Processing fees, legal and valuation charges and documentation charges are paid once. Compare them across lenders; together they are part of your real cost.
4. Insurance
Lenders often offer loan-protection insurance. It can be valuable for your family. Understand the cover and the premium, and choose it as a decision, not a default.
5. Prepayment flexibility
For floating-rate home loans taken by individuals, lenders do not charge a penalty for paying early. Every extra payment reduces your interest. A bonus or a salary increase can bring your loan end date closer.
6. Tenure
A longer tenure lowers your EMI and raises your eligibility. A shorter tenure lowers your total interest. Many buyers choose a longer tenure for comfort and prepay when they can, which gives them both.
A quick example
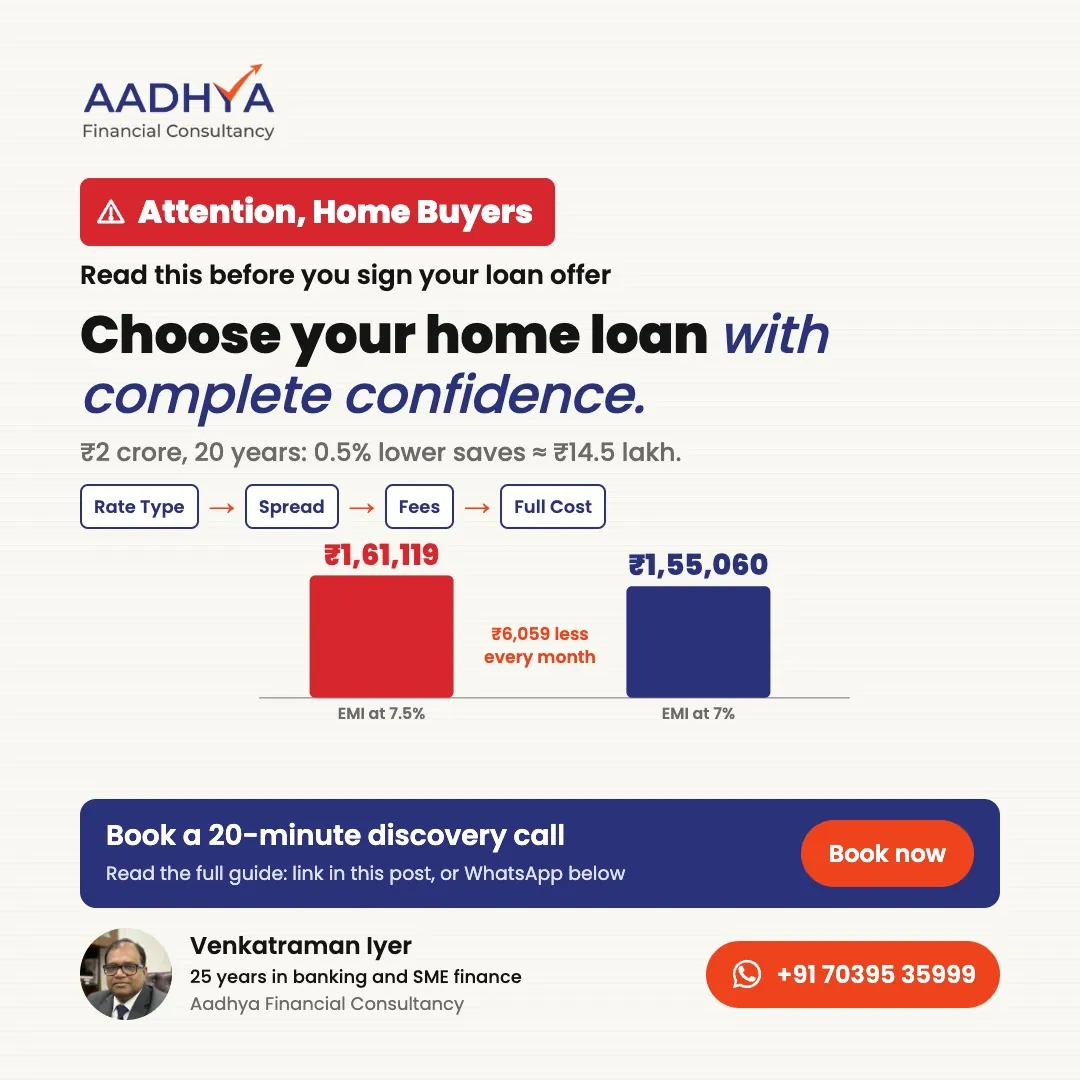
On a Rs 2 crore loan over 20 years, a rate just 0.5% lower (7% instead of 7.5%) saves about Rs 6,059 every month, or about Rs 14.5 lakh over the life of the loan. That is why the spread you start with matters so much.
Figures are illustrations, not an offer. Try your own numbers in the EMI calculator.
Do it yourself, or have me by your side
You can compare these six points across lenders yourself.
Or I can lay offers side by side for you, compare the full cost, present your profile so it earns the best spread, and stay with you until the loan is running.
Frequently asked questions
Is a floating or fixed home loan better?
Most buyers choose floating, as it usually starts lower and benefits when rates fall. A fixed rate suits those who value a steady EMI over a set period.
Can I prepay my home loan without a penalty?
For floating-rate home loans taken by individuals, lenders do not charge a prepayment penalty.
What is the spread on a home loan?
It is the margin the lender adds over the benchmark rate. It is fixed for your profile at the start, so a strong profile saves money for the whole loan.
Your next step
In a 20-minute discovery call, we'll look at your options and what the full cost of each would be for you.
Book a 20-minute discovery call There's no pressure. We'll just see if we can help.
Read more: Home loans for salaried professionals
Disclaimer: This article is for general information only and is not financial advice. Aadhya Financial Consultancy is a loan advisory firm working with banks and NBFCs; it does not lend. Rates, fees and terms depend on each lender and on RBI rules in force.
I spent 15 years inside banks learning how a lender reads a loan. Since 2017, I've used it only on the borrower's side.
More about me →