How to find out exactly how much home loan your salary qualifies for, in 10 minutes, even if part of your pay is variable.
Most salaried professionals start their home search with one question in mind: "How much will the bank give me?" The good news is that you don't have to wait for a bank to tell you. Your eligibility follows a simple logic, and once you see it, you can plan your home with confidence.
The new way to look at eligibility
Think of your home loan eligibility as a number you can work out and improve, not a verdict from a bank. Lenders look at one central question: how much of your monthly salary can comfortably go towards EMIs. Everything else follows from that.
The 10-minute method
- Start with your take-home salary. Use the amount that reaches your account each month.
- Work out your EMI room. Lenders allow a share of your take-home salary for all EMIs together. The share varies by lender and is higher for higher incomes; for this example we use 75%.
- Take away your existing EMIs. Car loan, personal loan, consumer EMIs: what is left is your room for the home loan EMI.
- Turn that EMI into a loan amount. At a given rate and tenure, every Rs 1 lakh of loan has a fixed EMI. Divide your EMI room by that figure.
A worked example
Priya earns a take-home salary of Rs 1,50,000 a month and pays a car loan EMI of Rs 15,000.
- EMI room: 75% of Rs 1,50,000 = Rs 1,12,500
- Less her car loan EMI: Rs 1,12,500 − Rs 15,000 = Rs 97,500 a month for her home loan
- At 7% for 20 years, each Rs 1 lakh of loan costs about Rs 775 a month, so she can borrow about Rs 1.26 crore
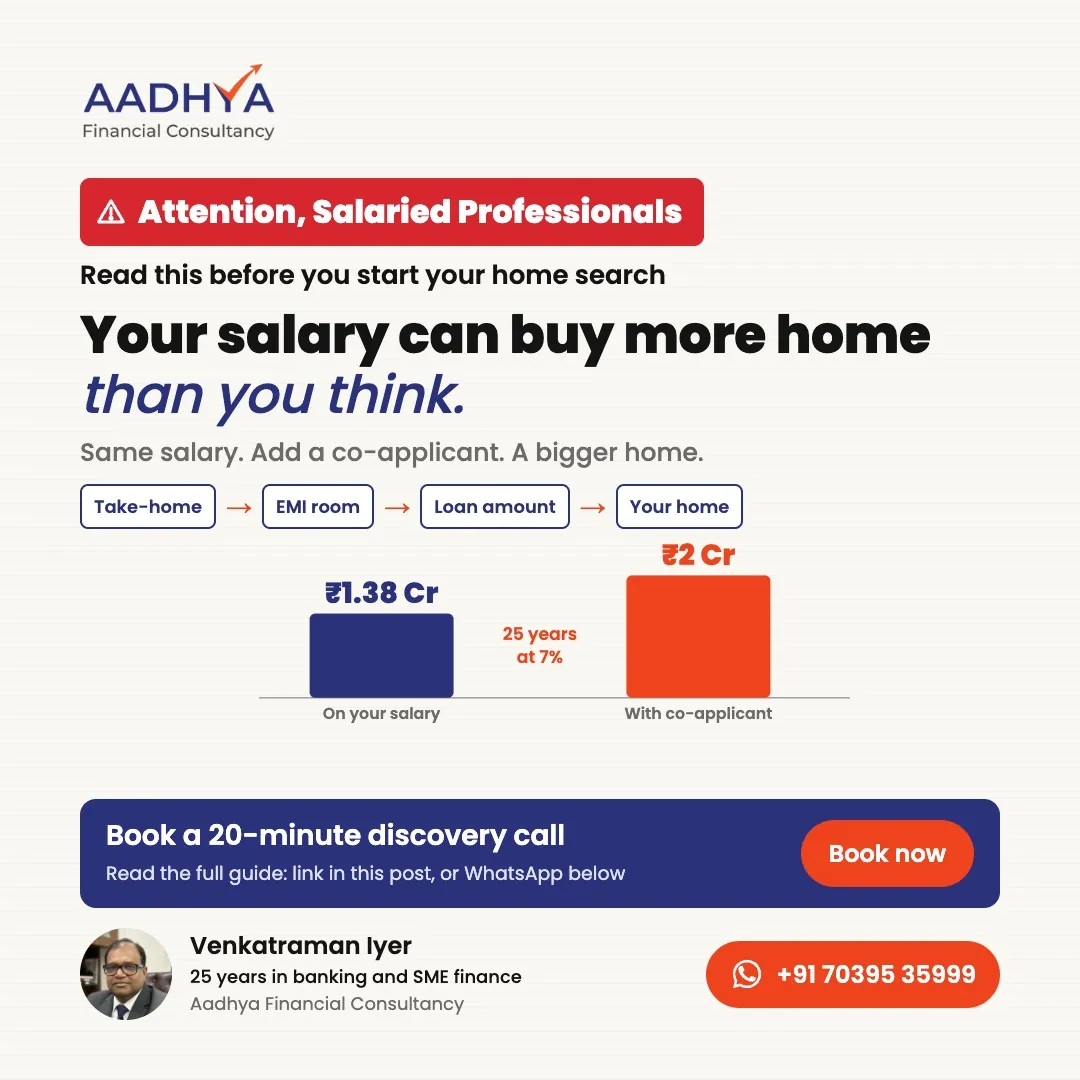
- Over 25 years, each Rs 1 lakh costs about Rs 707 a month, so the same EMI supports about Rs 1.38 crore
Now her husband joins as co-applicant. He takes home Rs 60,000 a month, which adds Rs 45,000 of EMI room. Together, Rs 1,42,500 a month over 25 years supports a loan of about Rs 2 crore.
Figures are illustrations to show the method, not an offer. Each lender has its own policy.
Four ways to grow your eligibility
- Add an earning co-applicant. A spouse or parent can add their income to yours.
- Choose a comfortable tenure. A longer tenure lowers the EMI on each lakh, so the same salary supports a larger loan.
- Close small loans before you apply. Every EMI you clear adds directly to your home loan room.
- Keep your credit record strong. On-time EMIs and card payments open the best rates, and a better rate means more loan for the same EMI.
Use the EMI calculator to try your own numbers.
Do it yourself, or have me by your side
You can follow the method above, compare a few lenders and apply. It works, and many people do it.
Or you can have a banker's eye on your application. I work out your eligibility the way a credit officer does, show you how to grow it, and take your application only to the lenders whose policy suits your profile. Then I stay with you until the money is released.
Frequently asked questions
How much home loan can I get on a Rs 1 lakh salary?
It depends on your existing EMIs, the tenure and the lender. With no other EMIs, Rs 1 lakh take-home can support a loan of about Rs 1.06 crore over 25 years at 7%, using the 75% guide above. A co-applicant can increase it.
Does a longer tenure increase my eligibility?
Yes. A longer tenure lowers the EMI for each lakh, so your salary supports a larger loan.
Can my spouse be a co-applicant?
Yes. An earning spouse or parent as co-applicant adds their income to the calculation.
Your next step
In a 20-minute discovery call, you'll know roughly how much you can borrow, which lenders suit your profile, and how to strengthen your application.
Book a 20-minute discovery call There's no pressure. We'll just see if we can help.
Read more: Home loans for salaried professionals
Disclaimer: This article is for general information only and is not financial advice. Aadhya Financial Consultancy is a loan advisory firm working with banks and NBFCs; it does not lend. Eligibility, rates and terms depend on each lender's assessment. Figures are illustrations.
I spent 15 years inside banks learning how a lender reads a loan. Since 2017, I've used it only on the borrower's side.
More about me →