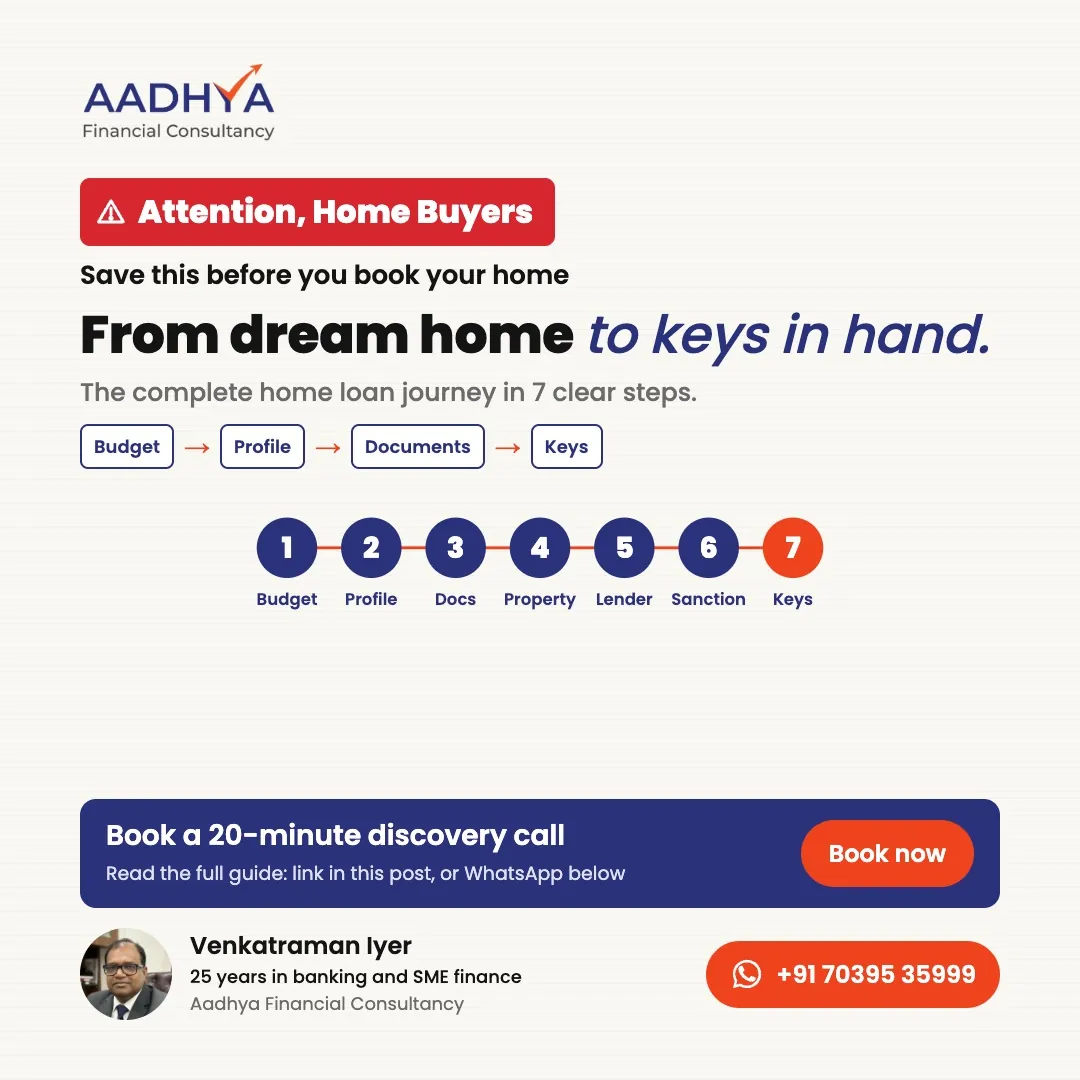
How to go from "I want a home" to "keys in hand" in 7 clear steps, with every step covered, even if this is your first home.
Buying a home feels big because it is. But a home loan is not one giant leap. It is a sequence of small, predictable steps. When you know the order, each step becomes simple. Keep this checklist handy and tick as you go.
The new way to look at it
Plan the loan before you choose the home. When you know your budget and your lender options first, you shop with confidence and negotiate with clarity.
The 7-step home loan checklist
Step 1. Know your budget
- Work out how much loan your salary supports (see the guide)
- Decide your own contribution (down payment)
- Add the costs beyond the price: stamp duty, registration, legal and processing fees, interiors
Step 2. Strengthen your profile
- Check your credit report and keep every EMI and card payment on time
- Close small loans where you can
- Decide whether an earning spouse or parent will be co-applicant
Step 3. Get your documents ready
- Identity and address proof
- Last 3 months' salary slips
- 6 months' salary account statements
- Form 16 or ITR for the last 2 years
- Details of existing loans
Step 4. Choose the property
- Shortlist homes within your budget
- Check the property (see what to verify)
- Prefer projects already approved by several lenders
Step 5. Choose the lender
- Compare the full cost, not only the rate (see what to understand)
- Apply to the lenders whose policy suits your profile
Step 6. Sanction and agreement
- Read the sanction letter: amount, rate, tenure, fees, conditions
- Sign the agreement for sale and pay stamp duty and registration
- Submit the property papers for the lender's legal and technical check
Step 7. Disbursement and keys
- Pay your own contribution as agreed
- The lender releases the loan to the seller or builder
- For an under-construction home, funds are released in stages as construction progresses
Do it yourself, or have me by your side
You can follow this checklist yourself, one step at a time.
Or I can walk it with you: work out your budget, check your papers the way a bank would, choose the lenders that suit your profile, and stay with you from sanction to the day you receive your keys.
Frequently asked questions
What documents do I need for a home loan?
Identity and address proof, recent salary slips, salary account statements, Form 16 or ITR, details of existing loans, and the property papers.
Should I choose the home or the loan first?
Know your loan budget first. It lets you shop with confidence and negotiate well.
How long does a home loan take?
With complete documents and an approved property, sanction can be quick. The legal and technical checks of the property usually decide the timeline.
Your next step
In a 20-minute discovery call, we'll go through this checklist for your situation, and you'll know exactly what to do next.
Book a 20-minute discovery call There's no pressure. We'll just see if we can help.
Read more: Home loans for salaried professionals
Disclaimer: This article is for general information only and is not financial or legal advice. Aadhya Financial Consultancy is a loan advisory firm working with banks and NBFCs; it does not lend. Requirements vary by lender and state.
I spent 15 years inside banks learning how a lender reads a loan. Since 2017, I've used it only on the borrower's side.
More about me →