For SMEs with Rs 10 crore+ turnover · Thane & Mumbai
Project finance for SMEs in Thane and Mumbai: Your new plant, from plan to first production.
- Funding shaped to your project
- Without waiting for revenue
- Even if it's your biggest yet
What clients say
5.0 ★ on Google, 27 reviewsProject finance for a new unit or plant · Thane & Mumbai
Your new plant, planned to succeed.
Your plant built and running on plan, without pausing midway for funds, even if costs move during construction.
A sound project succeeds when repayment starts after revenue does. That's decided in the structure.
How we helpWe read the project the way a credit committee will and set the contribution, moratorium and working capital right.
Tell us four things and we'll send your exact list on WhatsApp.
Expansion finance for SMEs · Thane & Mumbai
Fund your next big expansion, with every limit in balance.
Funds for a large expansion, without disturbing your existing limits, even if you bank with more than one lender.
Expansion funding works best when the new and existing limits are planned together.
How we helpWe plan the expansion loan alongside your current limits, so the whole structure stays balanced.
Tell us four things and we'll send your exact list on WhatsApp.
Project loan takeover for SMEs · Thane & Mumbai
Your project loan, on terms that suit it today.
Better terms for your running project loan, without a fresh application from zero, even if the project is still ramping up.
An existing project loan can often move to a lender whose terms suit the project today.
How we helpWe compare the full cost and terms, and move it only when it clearly pays.
Tell us four things and we'll send your exact list on WhatsApp.
From first call to funds in your account
From project report to first disbursement, without visiting bank after bank, even if your project report is still being prepared.
Review
Your balance sheet read the way a credit officer reads it.
Structure
The right product for each need.
Match
Only lenders keen on businesses like yours.
Disburse
With you until the money reaches your account.
Our commitment: we work to get you the full amount your plan needs, so every part of it is covered.
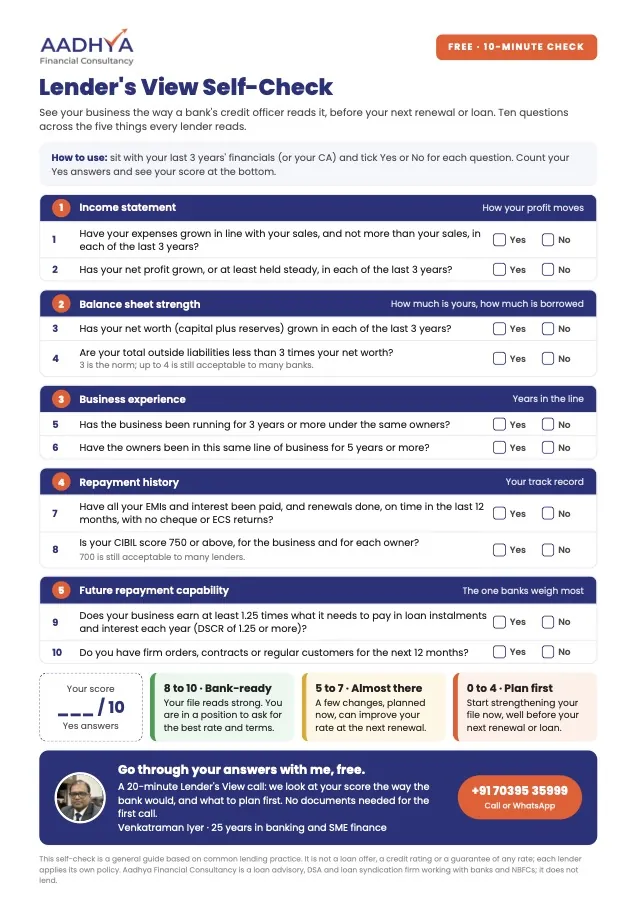
Lender's View Self-Check
See your business the way a bank's credit officer reads it, before your next renewal or loan. Ten Yes or No questions across the five things every lender reads, and your score in 10 minutes.
- Your score out of 10
- Where your file is strong, and where to plan first
- Done with your last 3 years' financials, or with your CA
Project finance questions, answered
How much do I need to bring in for a project?
Lenders usually expect the promoter to fund a part of the project cost. The share depends on the project, the industry and the lender.
What is a moratorium?
A period at the start when repayment is paused or reduced, so the loan is repaid from the project's revenue rather than before it.
Do I need a project report?
Yes. A clear project report with costs, means of finance and projections is the base of every project loan. We review it the way a credit committee will.
Can more than one lender fund the project?
Yes. Large projects are often funded by two or more lenders together.
Your next step: two simple steps
Start with a call. If a full review is worth your time, we take it from there.
20-minute Lender's View call
Tell us about your business and your current bank facilities. We'll tell you how a credit officer is likely to read your profile, and whether a full review is worth your time.
Book my Lender's View callBalance Sheet Review
You share the last 2 years' audited financials, the current year's provisional figures and your current sanction letter(s). We study them the way a credit officer does, against everything a lender reads. Free for 5 businesses a month; we'll offer it on the call if it fits. In a 45-minute meeting you get a one-page report:
- Where you stand on everything a lender reads
- What to strengthen before the year closes
- Which lenders are keen on a profile like yours
There's no pressure. We'll just see if we can help.