Home loan and loan against property for self-employed business owners and professionals in Thane and Mumbai: There's more to your business than your ITR.
- A 360° view of your business
- Without extra effort on your side
- Even if you earn in many ways
What clients say
5.0 ★ on Google, 27 reviewsWhat the bank reads in a business owner's profile
Every lender reads these four things. Present them well, and the right loan follows.
Your income as per ITR
- Profit after tax
- Depreciation added back
- The 2 to 3 year trend
Your banking and credit
- Average balances
- No cheque returns
- Credit score
Your business
- Years in business
- GST in line with ITR
- Steady income
The property
- Clear title
- Approvals in place
- Complete papers
Three ways to strengthen your application
Plan tax and loan together
- Talk to your CA early
- Before the year closes
Keep one clean main account
- 6 to 12 months
- No cheque returns
Choose the lender first
- Lenders that read business income well
- One well-placed application
From first call to funds in your account
The right loan for your next big step, without extra effort on your side, even if your income comes from more than one source.
Review
Your ITR, banking and GST read the way a bank reads them, before you apply.
Match
Only lenders whose policy suits a business owner like you.
Compare
Rate, fees and terms of every offer, side by side.
Disburse
With you until the money reaches your account.
Our commitment: we work to get you the full amount your plan needs, so every part of it is covered.
Home Loan & LAP Calculators
Know your EMI, affordability and saving before you speak to any bank.
EMI calculator
Your monthly EMI and total interest.
Calculate →Affordability calculator
The loan your comfortable EMI gets.
Calculate →Balance transfer calculator
Your saving at a lower rate.
Calculate →LAP EMI calculator
EMI on a loan against property.
Calculate →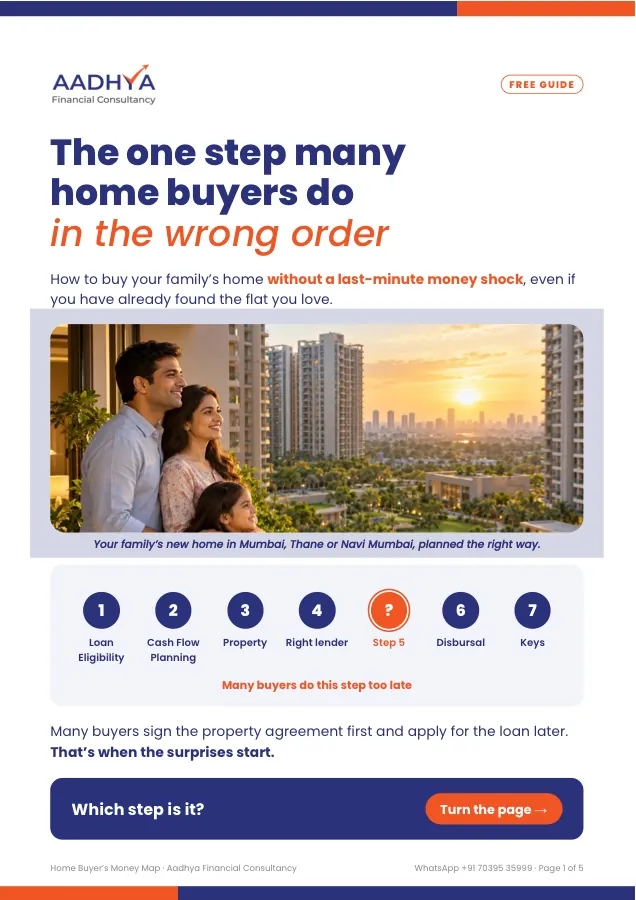
Home Buyer's Money Map
One step, done at the right time, keeps your whole home budget on track. This short guide shows you which step it is, and the 7 steps from "Can I afford it?" to the keys in your hand.
- The step to do before you sign
- The full cash plan, beyond the loan
- A worksheet for your own numbers
Questions business owners ask
How do banks work out a self-employed person's income?
Mostly from your last 2 to 3 years' ITR: profit after tax, with depreciation and some other items added back. Some lenders also read your banking or GST turnover. Each lender's method is different, which is why choosing the lender first matters.
My CA keeps my profit low to save tax. Can I still get a good loan?
Often, yes. Some lenders have programmes that look beyond declared profit, and the right planning before the year closes helps too. We'll show you what your papers support and which lender reads them best.
How many years in business do I need?
Most lenders look for at least 3 years in the same business or practice, with ITRs filed for those years.
Can I move my home loan to a lower rate?
Yes. A balance transfer moves your outstanding loan to a new lender at a lower rate. We check that the saving is more than the costs before you move.
Can I take a loan against property for my business?
Yes. A self-occupied or let-out home, office, shop or godown can raise long-term funds for the business, usually at a lower cost than an unsecured business loan.
What documents does a self-employed person need?
Typically your last 2 to 3 years' ITR with computation, 12 months' main bank account statement, GST return summary, details of existing loans and the property papers. We give you a checklist for your case.
Your next step: a 20-minute discovery call
In 20 minutes you'll know:
- Roughly how much your business income supports
- Which lenders suit your profile
- What to set right before you apply
There's no pressure. We'll just see if we can help.