For SMEs with Rs 10 crore+ turnover · Thane & Mumbai
Working capital finance for SMEs in Thane and Mumbai: Your orders keep moving, and your suppliers get paid on time.
- The right limit for your growth
- Without giving up tax savings
- Even if growth is ahead of books
What clients say
5.0 ★ on Google, 27 reviewsCash credit and overdraft for SMEs · Thane & Mumbai
Day-to-day funds, always ready.
Your CC or OD limit sized to your real trade cycle, without idle money costing you interest, even if your business is seasonal.
Same bank. Same loan. One owner pays 8%, the other 10%. The difference is how the file is presented.
How we helpWe read your balance sheet like a credit officer, set the structure right before the year closes, and match you to a lender keen on your business.
Tell us four things and we'll send your exact list on WhatsApp.
Letter of credit and bank guarantee for SMEs · Thane & Mumbai
Trade with confidence, backed by the right limits.
LC and BG limits sized to your trade, without blocking your cash limits, even if your suppliers want more security.
Non-fund limits can cost far less than cash limits, and free up your CC for daily needs.
How we helpWe size the LC and BG limits to your real trade cycle, and negotiate the commission and margin.
Tell us four things and we'll send your exact list on WhatsApp.
Export finance for SMEs · Thane & Mumbai
Ship more, get paid sooner.
Funds for every shipment, without stretching your CC, even if your buyers pay late.
Pre- and post-shipment credit can be cheaper than your CC, when it's set up right.
How we helpWe set up packing credit and bill discounting that fit your shipment cycle.
Tell us four things and we'll send your exact list on WhatsApp.
Supply chain finance for SMEs · Thane & Mumbai
Suppliers paid on time, customers given time.
Free up your working capital using your customers' strength, often without extra property security, even if your CC is fully used.
Your customer pays in 90 days and your supplier wants 30. Their strength can fund the gap, at a lower cost than your CC.
How we helpWe look at your buyers, suppliers and limits together, and set up the discounting lines that free your CC.
Tell us four things and we'll send your exact list on WhatsApp.
What happened when the file was presented the right way
From first call to funds in your account
Working capital that keeps your business moving, without visiting bank after bank, even if you've banked with the same lender for years.
Review
Your balance sheet read the way a credit officer reads it.
Structure
The right product for each need.
Match
Only lenders keen on businesses like yours.
Disburse
With you until the money reaches your account.
Our commitment: we work to get you the full amount your plan needs, so every part of it is covered.
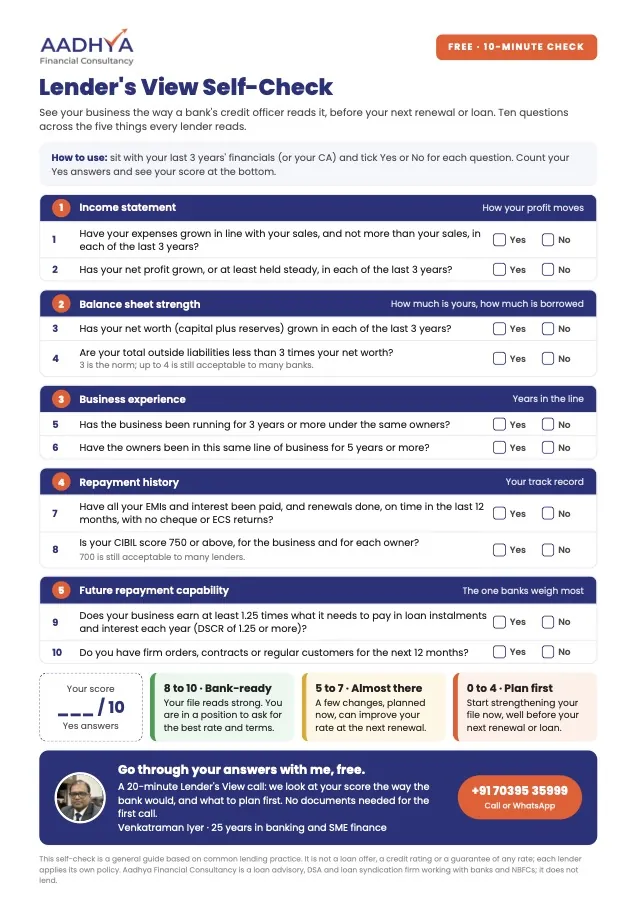
Lender's View Self-Check
See your business the way a bank's credit officer reads it, before your next renewal or loan. Ten Yes or No questions across the five things every lender reads, and your score in 10 minutes.
- Your score out of 10
- Where your file is strong, and where to plan first
- Done with your last 3 years' financials, or with your CA
Working capital questions, answered
Does lowering my profit to save tax affect my limit?
Yes. Lenders size your limit on the profit and balance sheet you file, so planning profit down to save tax can shrink the limit you get. We help you and your CA find the balance, so you keep your tax savings, and your file still reads strong to a lender.
How is my working capital limit worked out?
From your stock, receivables and payables, your turnover and your financials. Lenders use different methods, so the same business can get different limits.
Can I lower the rate on my existing CC or OD?
Often, yes: by presenting your financials better, restructuring the limits, or moving to a lender whose policy suits you. We check the full cost before you move.
What is supply chain finance?
Discounting of your sales or purchase bills, based on the strength of your buyer or supplier. It often costs less than your CC and frees your limit.
Do LC and BG limits need cash margin?
Usually some margin is needed. The amount is negotiable and depends on your profile and the lender.
Your next step: two simple steps
Start with a call. If a full review is worth your time, we take it from there.
20-minute Lender's View call
Tell us about your business and your current bank facilities. We'll tell you how a credit officer is likely to read your profile, and whether a full review is worth your time.
Book my Lender's View callBalance Sheet Review
You share the last 2 years' audited financials, the current year's provisional figures and your current sanction letter(s). We study them the way a credit officer does, against everything a lender reads. Free for 5 businesses a month; we'll offer it on the call if it fits. In a 45-minute meeting you get a one-page report:
- Where you stand on everything a lender reads
- What to strengthen before the year closes
- Which lenders are keen on a profile like yours
There's no pressure. We'll just see if we can help.