How to raise funds for renovation, education or a wedding at home-loan cost, with an EMI that stays easy, even if you're still paying your home loan.
Every family has its big moments: a child's higher education, a wedding, a home renovation, a second home. When those moments arrive, the question is simple: what is the smartest way to fund them?
The new way to look at your home loan
Your home loan is not only something you repay. Every EMI you have paid, and every rupee your home has gained in value, has built up your access to low-cost funds. A home loan top-up lets you use that access: extra funds added to your existing home loan, usually at a rate close to your home loan rate.
Top-up or personal loan: the numbers side by side
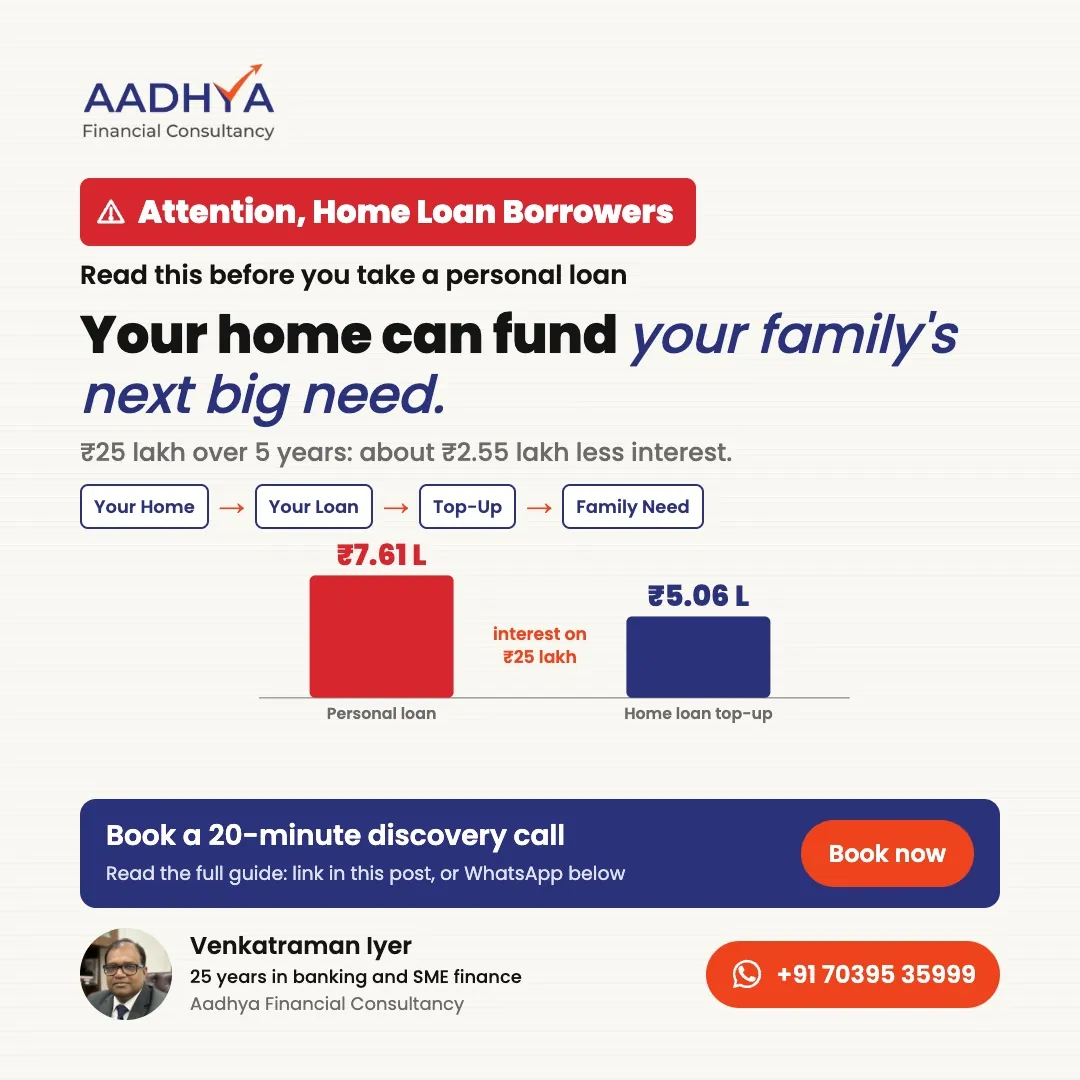
Suppose you need Rs 25 lakh, repaid over 5 years.
| Home loan top-up | Personal loan | |
|---|---|---|
| Rate (illustrative) | 7.5% | 11% |
| Monthly EMI | Rs 50,095 | Rs 54,356 |
| Total interest | Rs 5.06 lakh | Rs 7.61 lakh |
The top-up saves about Rs 2.55 lakh on the same Rs 25 lakh. And because a top-up can often run for a longer tenure, the same Rs 25 lakh over 10 years needs an EMI of about Rs 29,675, easy on a monthly budget.
Figures are illustrations to show the method, not an offer.
What makes a strong top-up application
- Your repayment record. A steady record on your home loan is your biggest strength.
- Your property's value. The top-up amount is based on what your home is worth today.
- Your salary and EMIs. Your income supports the new total EMI comfortably.
- The right timing. A top-up can be taken with your current lender, or along with a balance transfer, whichever gives you the better rate.
Popular uses of a top-up
Home renovation or extension · higher education in India or abroad · a family wedding · buying furniture and fittings for a new home · bringing costlier loans together into one easy EMI.
Do it yourself, or have me by your side
You can ask your current lender for a top-up offer and compare it with what others offer.
Or I can work out how much top-up your property supports, compare your current lender with others, including a transfer with a top-up, and recommend the option with the best full cost. Then I stay with you until the funds reach your account.
Frequently asked questions
Is a home loan top-up cheaper than a personal loan?
Usually, yes. A top-up is secured by your home, so lenders typically offer it at a rate close to your home loan rate, and for a longer tenure.
How much top-up can I get?
It depends on your property's current value, your outstanding loan, your salary and your repayment record.
Can I take a top-up while switching lenders?
Yes. Many lenders offer a top-up along with a balance transfer, in one process.
Your next step
In a 20-minute discovery call, you'll know roughly how much top-up you can get, which lenders suit you, and the best way to take it.
Book a 20-minute discovery call There's no pressure. We'll just see if we can help.
Read more: Home loan top-up for salaried professionals
Disclaimer: This article is for general information only and is not financial advice. Aadhya Financial Consultancy is a loan advisory firm working with banks and NBFCs; it does not lend. Rates and terms depend on each lender's assessment. Figures are illustrations.
I spent 15 years inside banks learning how a lender reads a loan. Since 2017, I've used it only on the borrower's side.
More about me →