In 30 seconds:
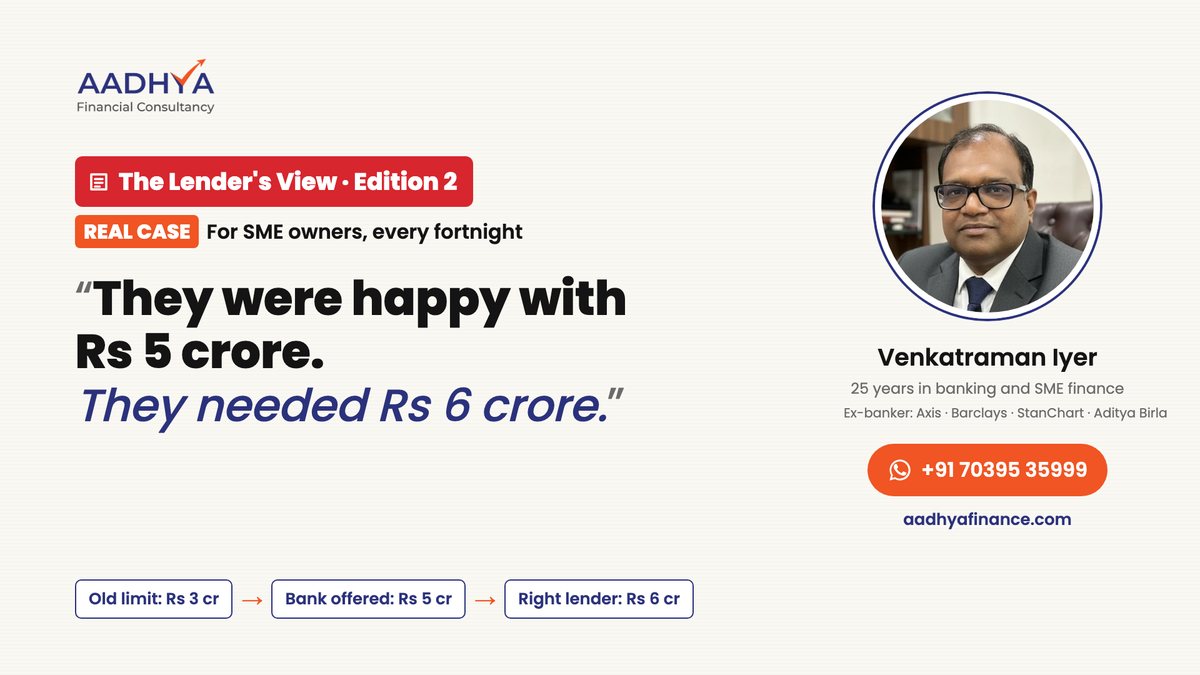
- A steel bar maker had a Rs 3 crore working capital limit.
- Steel prices jumped 26%. Suppliers stopped giving credit. Their need doubled to Rs 6 crore.
- Their bank sanctioned Rs 5 crore, and they were happy.
- Rs 5 crore would have left them Rs 1 crore short from day one.
- We got them the full Rs 6 crore from a lender who understands steel.
- Lesson: go with what you require, not with the bank's appetite.
A steel bar maker supplies the auto industry. Steady orders. Happy customers. A solid business.
Their working capital limit: Rs 3 crore. It was enough.
Until steel prices moved.
Then steel prices jumped
- Headline inflation: 6.09%
- TMT steel bars: up about 26% in a year
- HR coil: up about 32% in a year
The headline said 6%. For this company, the real inflation was 26%.
Your actual inflation can be far more shocking than the headline.
What is your industry's real inflation? Select your industry on our Industry Inflation Meter and see what it means for your working capital.
What happened on the ground
Their raw materials are steel wire rods and black bars. When prices jumped:
- Every tonne cost about 26% more
- Suppliers stopped giving credit. Advance payment only
- Their working capital need doubled: from Rs 3 crore to Rs 6 crore
- To manage, they stopped giving credit to their old customers, the higher-margin business
- They sold only to customers who paid upfront
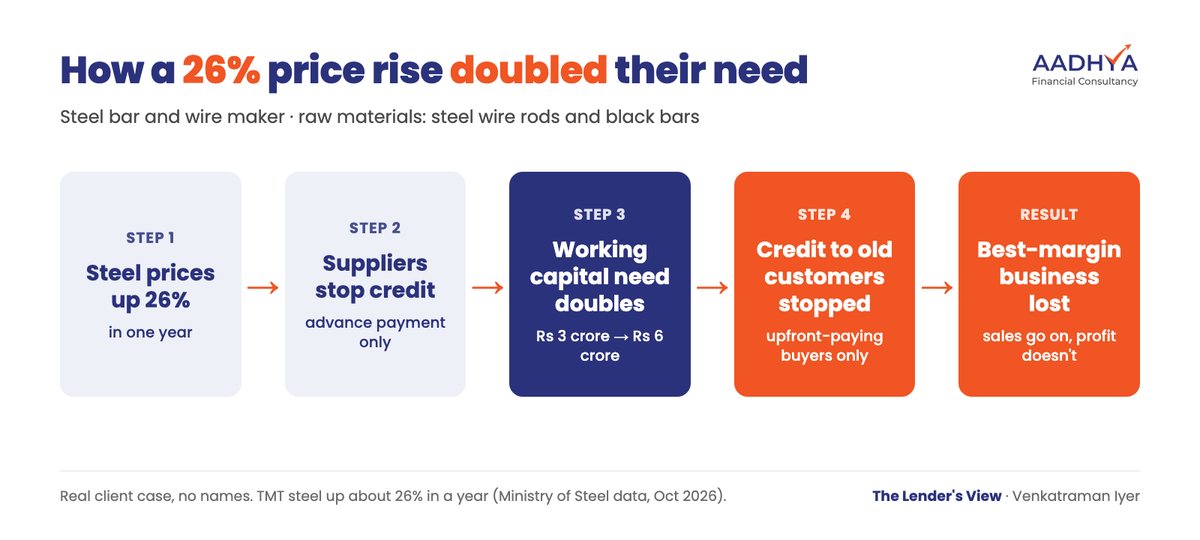
Sales continued. The owner worked harder than ever. But the best-margin business was slipping away.
Where is the profit?
The sanction that looked like good news
They applied for more. Their bank sanctioned Rs 5 crore. They were happy.
Then we sat down with them and went through the numbers:
- Existing limit: Rs 3 crore
- Actual requirement: Rs 6 crore, justified by steel prices and advance payments
- The bank's appetite: Rs 5 crore
Our advice was simple:
Go with what you require, not with the bank's appetite.
Rs 5 crore solves today's problem. Not tomorrow's.
Yes, Rs 5 crore would solve the immediate problem.
But they needed 6. So they'd be Rs 1 crore short from day one. And in the long term, that shortfall doesn't stay at Rs 1 crore. It keeps adding up, year after year. And it's the business owner who suffers.
I've seen this again and again in my 25 years in banking.
Why did the bank offer only Rs 5 crore?
Not because the business needed only 5.
Because the bank was comfortable only with 5.
Every lender has an appetite: for your industry, for your size, and for how much its branch can sanction.
So "We've assessed your need at Rs 5 crore" sometimes means "We're comfortable with Rs 5 crore." Most owners never find out which.
What we did
- Advised them not to settle for Rs 5 crore
- Showed why Rs 6 crore was justified: steel prices up 26%, and suppliers on advance payment
- Matched them with a lender that understands the steel industry
- Got the full Rs 6 crore sanctioned
- And this lender is ready to support them as steel prices move, not just at next year's renewal
Same business. Same numbers. Different lender.
That's the difference between 95 and 100.
100. Not 95. Not 105.
- 95 starves the business
- 105 spoils it: interest on idle money, and spare money drifts where it shouldn't
- 100 matches your cycle
How to find your 100
Headline inflation of 6.09% is an average of everything: vegetables, fuel, rent, school fees.
Your business doesn't buy everything. It buys your raw material. So your actual inflation can be far more shocking.
Your inflation is the price rise in what you buy.
- Your inflation: price per unit of your top 3 raw materials, last year vs today
- Your need today: stock + money customers owe you − money you owe suppliers
- Your 100: add your inflation on the raw material part. And if suppliers have moved from credit to advance payment, add that too. It can double your need
Your limit plus your own money well below this? You're at 95.
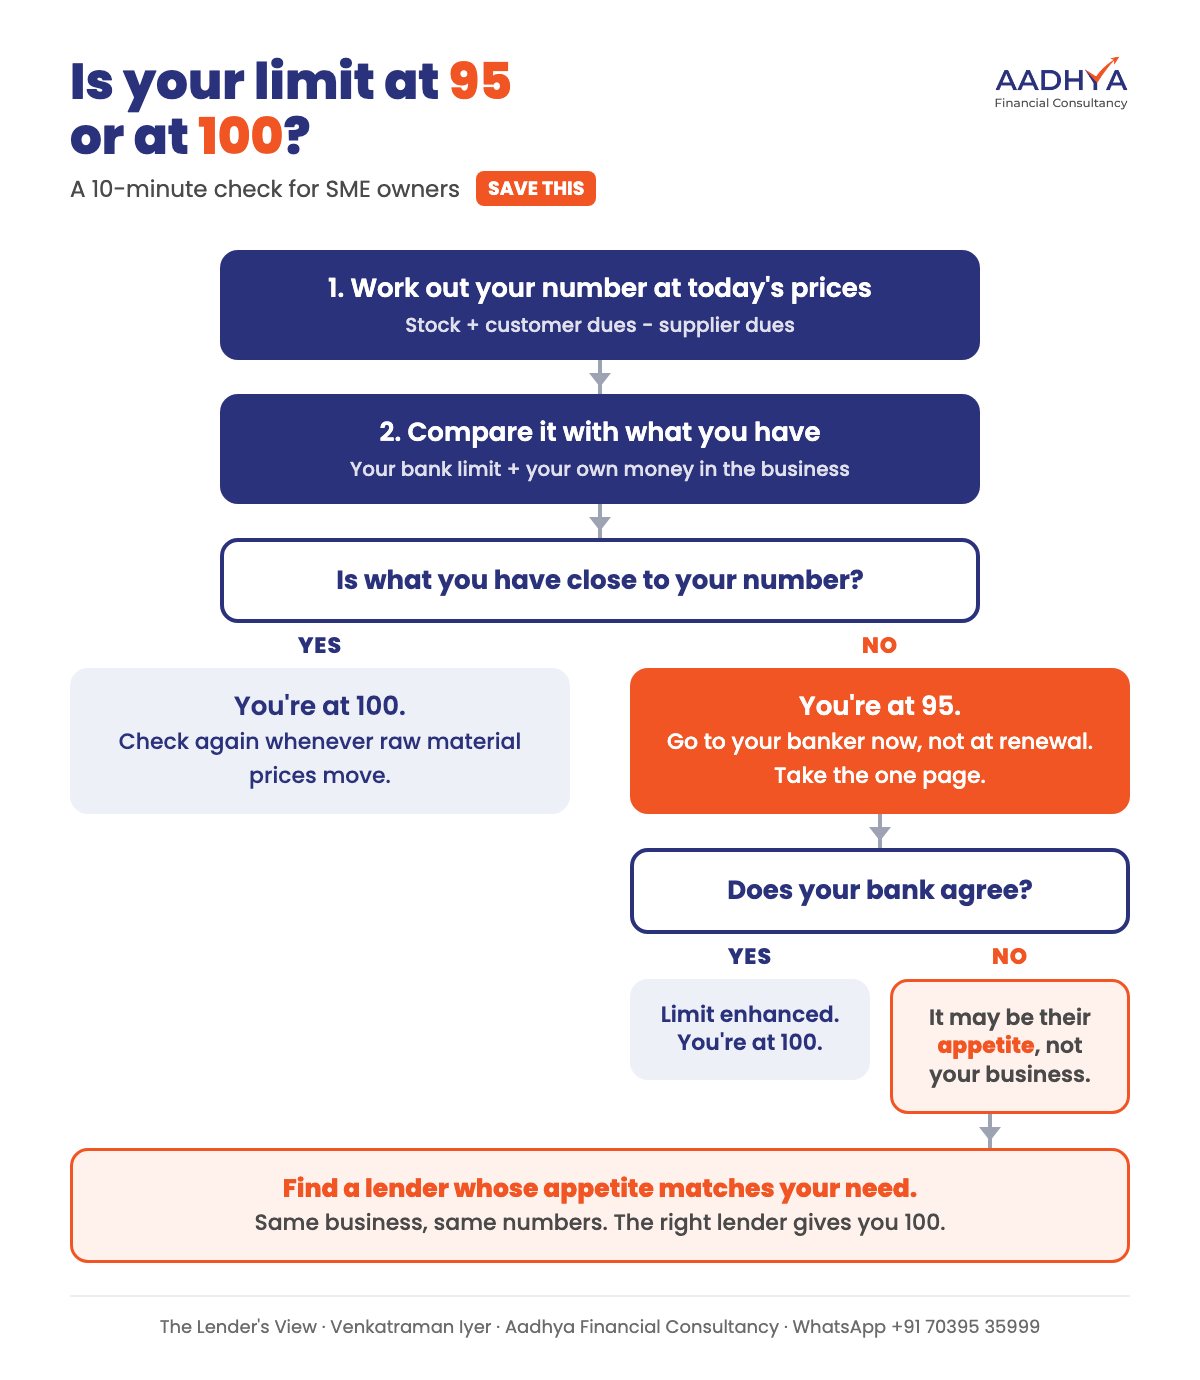
Short? Go to your banker now, not at renewal. Take one page:
- Limit and monthly usage, last 6 months
- Top 3 raw materials: quantity and price, last year vs today
- Supplier terms: credit days then, advance payment now
- Orders in hand, and orders refused
- Customer dues by age: 0-30, 31-60, 61-90, 90+ days
- Your new requirement, and how you worked it out
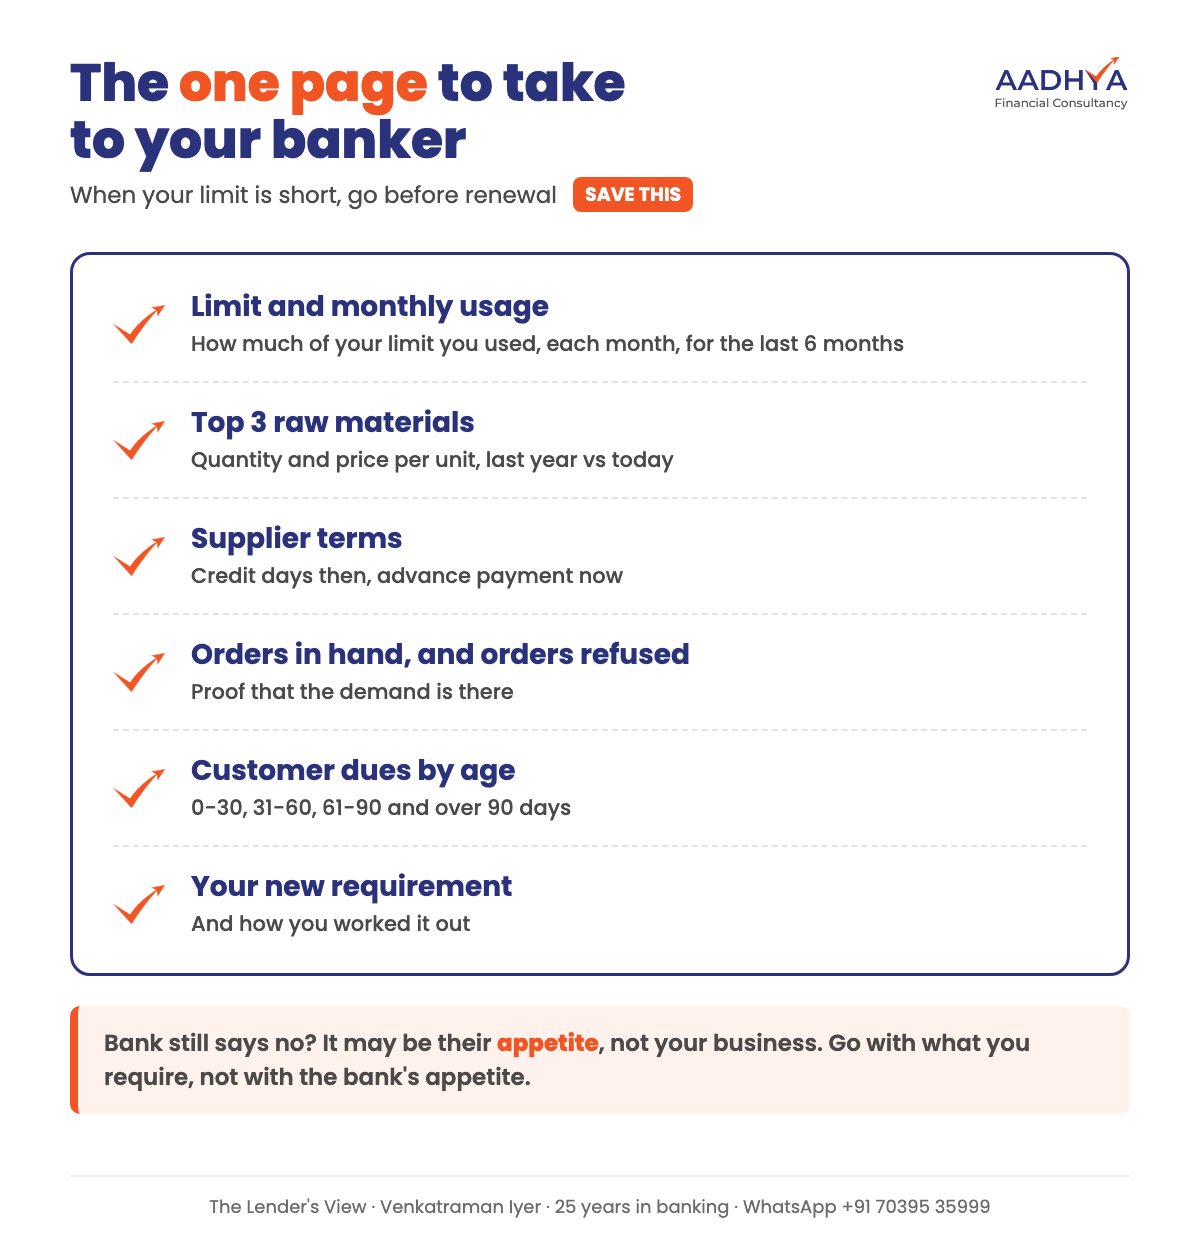
If the bank still says no, it may be their appetite, not your business. Find a lender whose appetite fits.
Common questions
Why does a bank sanction less working capital than I asked for?
Sometimes the assessment is genuinely lower. But often it reflects the bank's appetite: its comfort with your industry, your size, or the branch's sanctioning power.
Can I go to another lender if my bank offers less?
Yes. Different banks and NBFCs have different appetites. A lender that understands your industry may sanction your full requirement.
Does inflation increase my working capital need?
Yes. When raw material prices rise, the same quantity of stock costs more. If suppliers also move to advance payment, the need can rise much faster than prices.
Need your 100?
Book a free 20-minute Lender's View call. We work with 50+ banks and NBFCs to match your need with the right lender, just like we did for this steel company.
Or call +91 70395 35999. No documents needed for the first chat.
Sources: CPI October 2026: 6.09%, MoSPI press release, 12 Nov 2026. TMT (10 mm) Oct 2026 about Rs 66,645/t, +26.0% YoY; HR coil (2 mm) about Rs 77,620/t, +31.6% YoY: PIB release, Ministry of Steel data. Case: a real Aadhya Financial Consultancy client; names withheld. Every case is different: limits, rates and amounts are decided by the lender on its own assessment.
25 years in SME lending, with Axis Bank, Barclays, Standard Chartered and Aditya Birla Capital. Since 2017 he has worked only on the borrower's side, matching each business to the lender that fits it.
More about me →Part of The Lender's View, Venkatraman Iyer's LinkedIn newsletter.